Richardson extrapolation
Richardson extrapolation
ConceptCalculus and Analysis

Numerical method for accelerating convergence

1.25Uncommon
No. 21948Kosmora

Uncommon

Richardson extrapolation

  • Calculus and Analysis

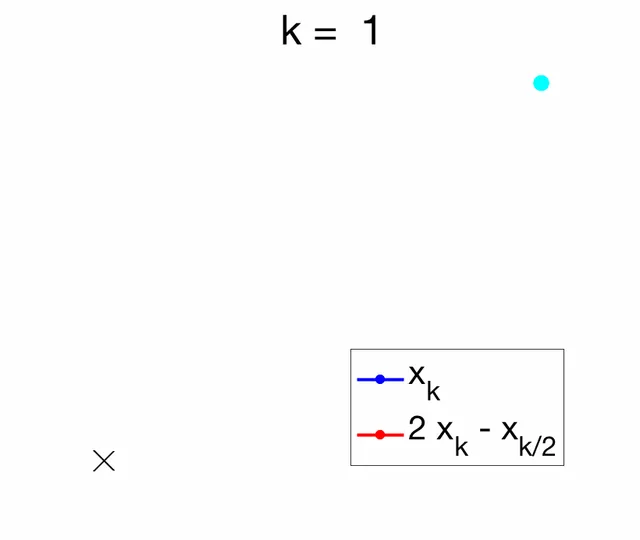
Richardson extrapolation is a numerical analysis method for estimating a limiting value when the truncation error has a possibly one-sided power-series expansion at zero. It is commonly used to accelerate the convergence of iterative methods. The technique is named after Lewis Fry Richardson, who introduced it in the early 20th century. Applications include Romberg integration and the Bulirsch–Stoer algorithm for ordinary differential equations.

Field
Numerical analysis
Typical use
Sequence acceleration
Applications
Romberg integration and the Bulirsch–Stoer algorithm
Sources and credits

Sources and credits

Article
Richardson extrapolation (English Wikipedia)
Wikidata
Q1063089
Text
Card text is adapted from the English Wikipedia article by an automated summary. Wikipedia content is available under CC BY-SA 4.0; see the article history for its contributors. CC BY-SA 4.0 · Article history and contributors
Illustration
By Francis Bach. CC BY-SA 4.0 · File page on Wikimedia Commons
Francis Bach, https://francisbach.com/home/
Modifications: Resized and converted to WebP
Popularity
50 median daily views (Wikimedia Pageviews API (all-access, user agent))

Kosmora is not affiliated with or endorsed by the Wikimedia Foundation.